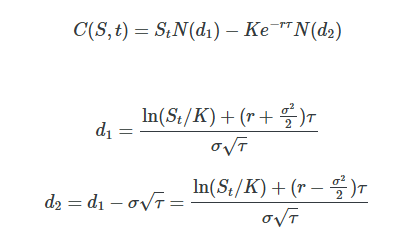A digital garden of my research into finance, market microstructure, and algorithms.
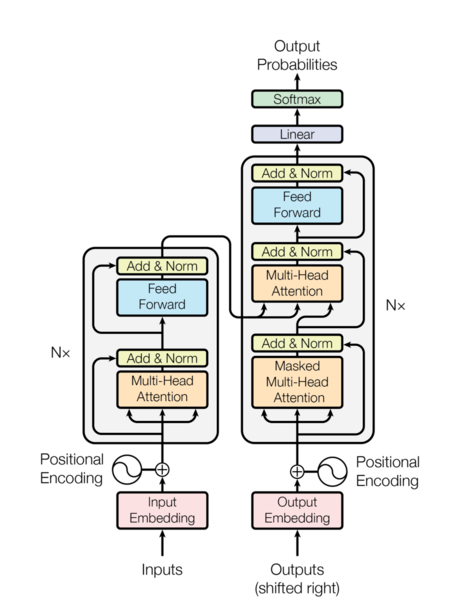
An analysis of the Attention Paper: Breaking down the Fundamental Concepts and Replication of the Model.
Analysis of Regulatory Change Regarding Equity Ownership and Related Analysis
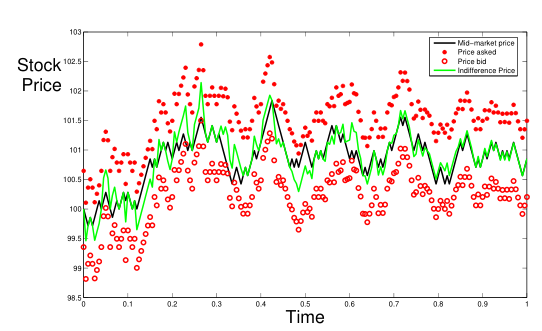
An analysis of the Avellaneda-Stoikov model: optimizing bid-ask spreads through utility theory, HJB equations, and inventory risk management.
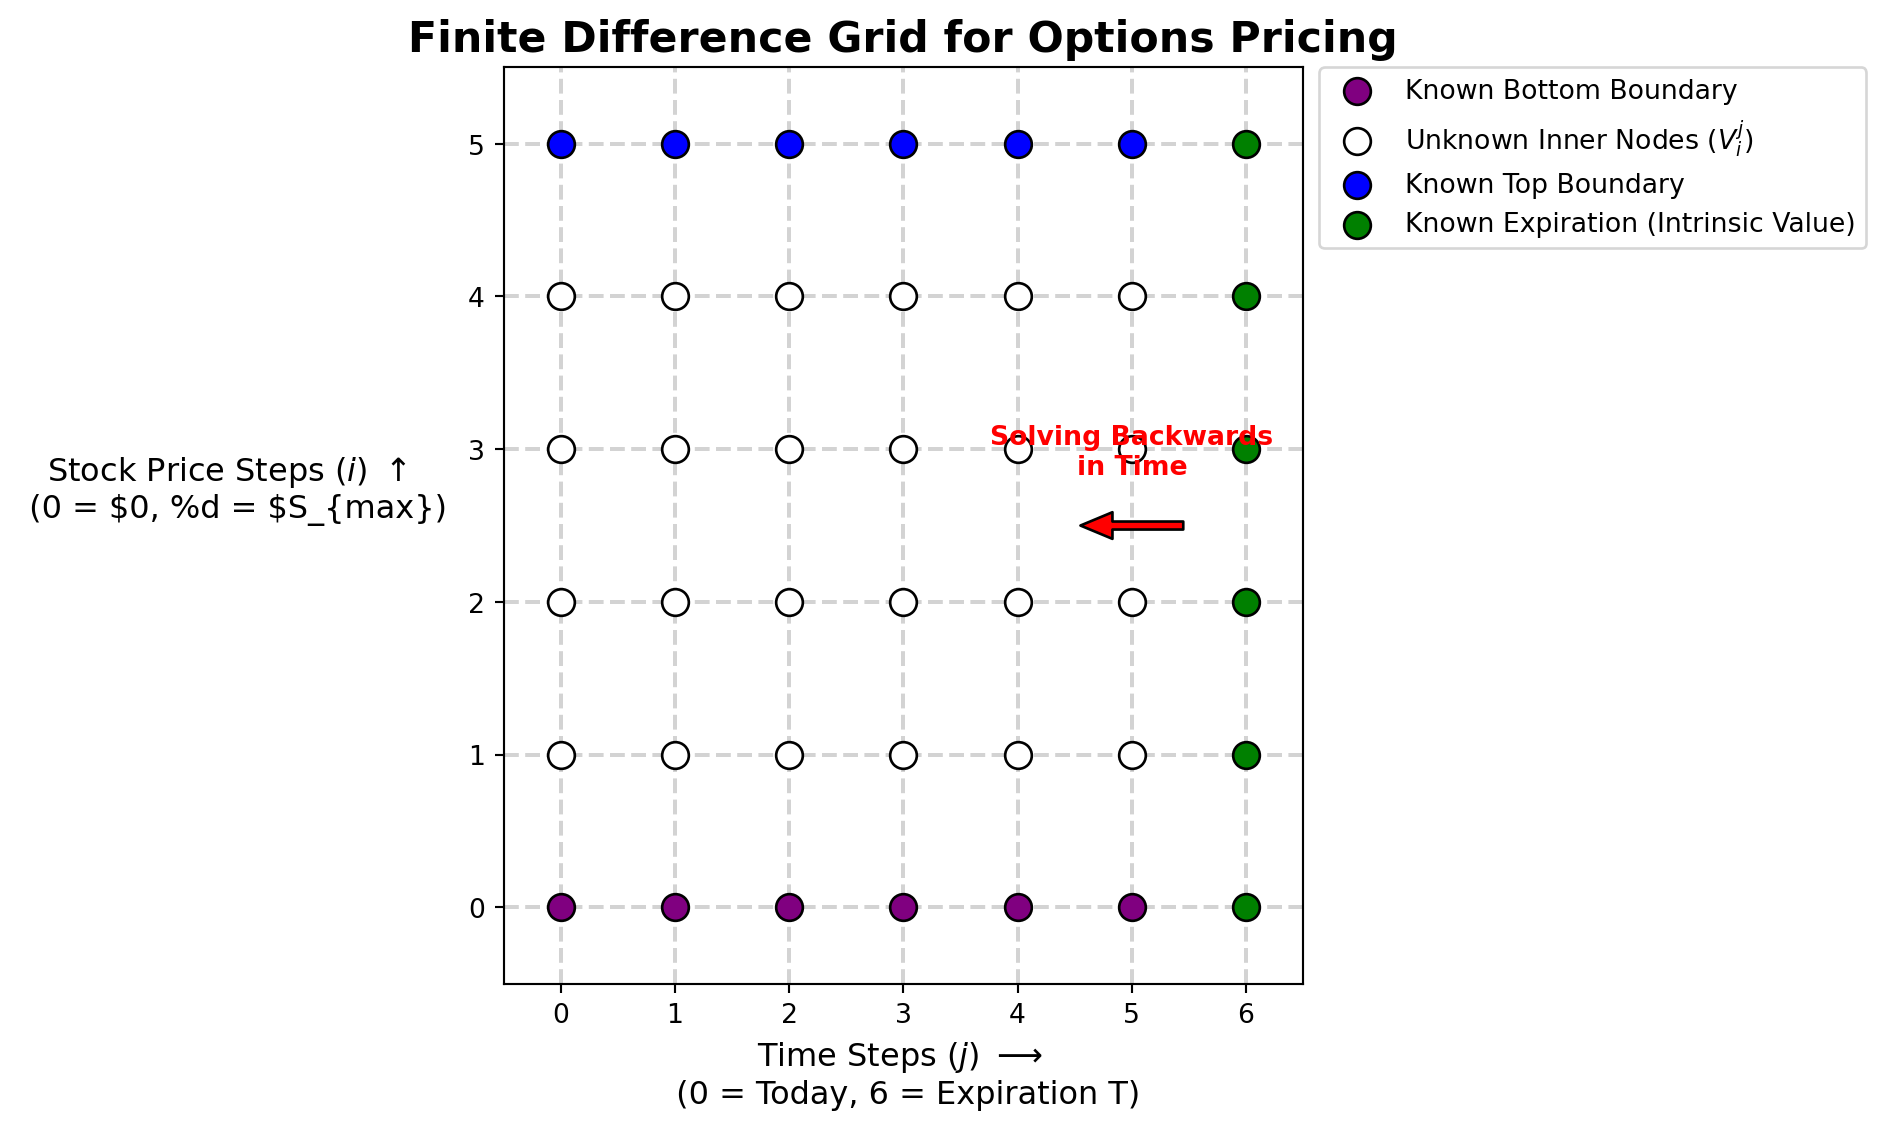
Solving the Black-Scholes PDE numerically stepwise.
A complete mathematical derivation of the Black-Scholes call option formula, from Geometric Brownian Motion to the final PDE and Feynman-Kac solution.
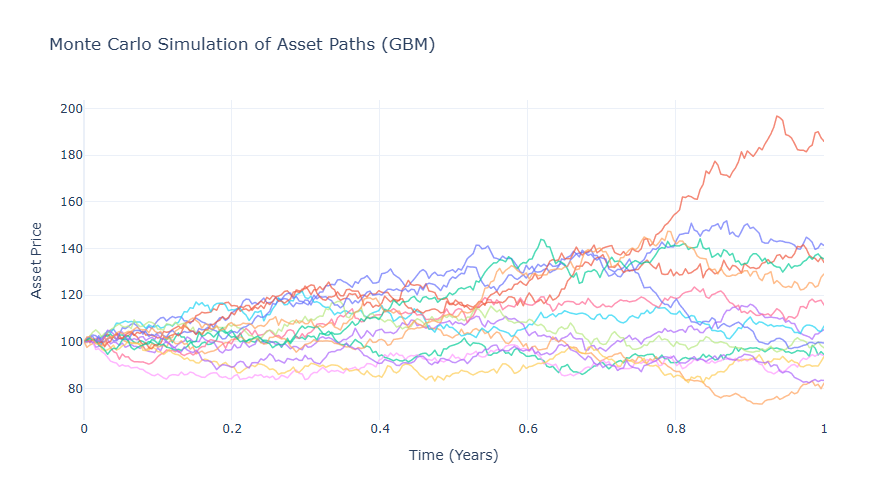
Theoretical option pricing models for the Black-Scholes, Heston, Merton and Bates models, to learn more about how they work and how they differ. Followed by testing based on…